Do You Get Your Deposit Back When a Secured Credit Card Graduates?
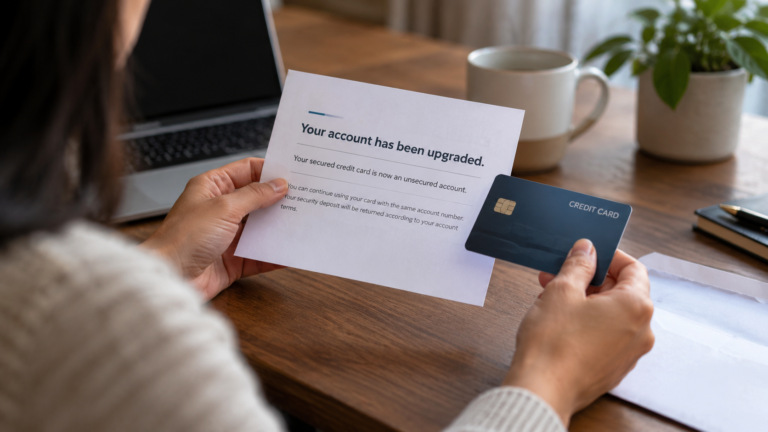
Yes, a secured credit card’s security deposit is generally returned when the issuer graduates the account to an unsecured card, but how and when you receive the money depends on the issuer.
That last part matters.
Your deposit might come back as a statement credit rather than cash deposited directly into your bank account. Another issuer may have a different refund process. And graduating an account is different from closing a secured card simply to recover the deposit.
So when you receive a graduation notice, don’t stop at:
“I’m getting my deposit back.”
Check what is actually happening to the money, the account and the card itself.
Why Did the Secured Card Require a Deposit in the First Place?
A secured credit card requires collateral, usually in the form of a refundable security deposit.
Depending on the card, you might deposit $200, $500 or another amount. The deposit helps secure the account for the issuer.
It is important to understand what that money is not.
Your security deposit is not normally a pool of money you spend every month. You still make purchases with the credit card and are responsible for paying the card balance according to the account terms.
The deposit sits behind the account as collateral.
That is the fundamental difference between a secured card and an unsecured credit card: an unsecured card doesn’t require that security deposit.
Current issuer guidance describes secured-card deposits as refundable collateral, although the exact deposit and refund policies vary by product and issuer. Capital One
What Happens to the Deposit When the Card Graduates?
When an issuer graduates—or “unsecures”—the account, it is removing the requirement for that collateral.
That creates an obvious question:
If the issuer no longer needs my deposit, where does my money go?
Generally, it is returned.
The CFPB has documented secured-card graduation as a process in which issuers with graduation programs return the consumer’s security deposit, although issuer practices and graduation policies differ. Consumer Financial Protection Bureau
The exact refund method is where things become more specific.
For example, Capital One currently states that when one of its eligible secured accounts is upgraded to a traditional unsecured card, the security deposit is returned as a statement credit. Capital One
That means you shouldn’t automatically expect a $200 deposit to become a $200 bank deposit.
Read the graduation notice.
It should be your first source for understanding what happens with your particular account.
Does a Statement Credit Mean You Get the Deposit Back?
Yes, but it changes what the refund looks like.
Suppose your issuer returns a $300 security deposit as a $300 statement credit.
If you currently have a balance, the credit may reduce what you owe.
If your account has little or no balance, the result may be a credit balance on the account, which the issuer handles according to its policies and applicable requirements.
The important distinction is:
Deposit returned doesn’t necessarily mean cash immediately appears in your checking account.
Check your account statement and issuer instructions before assuming something went wrong.
How Long Does It Take to Get a Secured Credit Card Deposit Back?
There isn’t one universal refund timetable that applies to every secured credit card.
Issuers establish their own procedures, and the process can also differ depending on why the deposit is being returned.
A deposit returned because your card graduated may be handled differently from a deposit returned because you closed the account.
That’s another reason not to use one issuer’s timeline as a promise for every secured card.
Look for the refund information in:
- Your graduation or upgrade notice
- Your cardholder agreement
- Your online account
- The issuer’s current secured-card information
- Information provided directly by the issuer
If the expected time has passed and you haven’t received the refund or credit, contact the issuer.
Is Getting Your Deposit Back the Same as Closing the Card?
No.
This is one of the most important distinctions in the secured-to-unsecured transition.
There are generally two different routes that can result in a security deposit being returned:
Graduation: The issuer converts or upgrades the account so it no longer requires the security deposit.
Closure: The secured account is closed and the issuer handles the deposit according to the account terms after outstanding obligations are addressed.
For example, Capital One currently identifies both an upgrade to an unsecured account and account closure as circumstances in which a secured-card deposit may be returned, but the refund procedures differ.
Those aren’t equivalent outcomes.
With graduation, you may be able to recover the deposit while continuing the account.
That can make graduation especially interesting because you don’t necessarily have to choose between getting your money back and keeping the credit-card account.
Don’t Close the Card Just to Get the Deposit Back Without Checking First
Imagine you’ve used a secured card for a while and now qualify for another credit card.
You might think:
“I don’t need this secured card anymore. I’ll close it and get my $500 back.”
That could be an available route.
But before doing it, check whether the existing card has a graduation process.
If your issuer might return the deposit without requiring you to close the account, that is a materially different option.
You can then evaluate the existing account on its own merits:
Does it charge an annual fee?
Does it still fit your spending?
Does it provide useful rewards?
What is the credit limit?
What is the APR?
Does the issuer offer another product path?
Is keeping the account useful to you?
Getting the deposit back is only one part of that decision.
What If You Still Owe Money on the Card?
A security deposit should not be treated as permission to stop making payments.
Your card balance and your security deposit are different things.
If the account remains open and graduates, follow the issuer’s instructions for the deposit refund and continue managing any card balance according to the account terms.
If you’re closing the account instead, the issuer may apply the security deposit against what you owe as part of the closing process.
Capital One, for example, currently says that when a secured account is closed, it applies the deposit to the account balance and handles any remaining refundable amount according to its stated process.
Your issuer’s current agreement controls your specific situation.
Does the Deposit Automatically Become Your New Credit Limit?
No.
This is an easy thing to mix up because secured-card deposits are often connected to the initial credit line.
But once the account graduates, there are several separate pieces to consider:
Security deposit — the collateral that secured the account.
Credit limit — how much credit the issuer makes available.
Card balance — how much you currently owe.
Available credit — the unused portion of your credit line.
Returning your deposit doesn’t necessarily mean the same amount gets added to your credit limit.
Capital One, for example, currently states for its Platinum Secured product that when the security deposit is returned and the account becomes unsecured, the other card terms and features remain the same. Capital One
So if you deposited $500, don’t automatically assume graduation means:
$500 returned + $500 increase in credit limit.
Check what actually changed.
Your CreditTerrain Deposit Checkpoint
When a secured card graduates, use this checkpoint before making another credit decision.
| Check | Question to Answer |
|---|---|
| Deposit amount | How much of my money is being returned? |
| Refund method | Statement credit, check, transfer or another method? |
| Refund timing | When does the issuer say it should happen? |
| Current balance | Do I currently owe money on the card? |
| Account status | Is the same account staying open? |
| Credit limit | Did my available credit change? |
| Annual fee | Does the card still cost anything to keep? |
| APR | Did the interest rate change? |
| Rewards | Are the rewards or benefits different? |
| Next step | Is there actually a reason for me to change anything else? |
That final question is important.
Getting your deposit back does not create an obligation to apply for another credit card.
Sometimes reaching the checkpoint is enough.
What Should You Do With the Returned Deposit?
Once the money is actually yours again, there is no universal “credit-building” rule requiring you to do something specific with it.
It’s your money.
You might move it back into savings, use it for another financial priority or simply leave it alone.
What I would not do is treat the returned deposit as a reason to spend more on the credit card.
Suppose you receive $500 back.
That doesn’t mean you’ve suddenly gained $500 of additional income.
You’ve recovered money that had previously been tied up as collateral.
That’s a meaningful difference.
Should You Use the Deposit to Pay Off the Credit Card?
That depends on how the issuer returns it and your particular balance.
If the issuer provides the refund as a statement credit, it may already reduce the account balance.
If you receive the deposit separately and you’re carrying expensive revolving debt, you can evaluate whether using some or all of the money toward that balance fits your financial situation.
But CreditTerrain wouldn’t automatically tell every reader to use the refund the same way.
The better approach is to understand:
What do I owe?
What is this debt costing me?
What other immediate needs do I have?
Then make the decision with the full picture in front of you.
What If Your Card Never Graduates?
A refundable security deposit doesn’t necessarily mean the issuer promises to graduate your account after a particular number of months.
Graduation policies vary.
Some issuers periodically review eligible accounts. Other products may work differently.
Capital One, for example, currently says it periodically reviews secured accounts for upgrade eligibility and that customers can’t simply request the upgrade. It also says there is no set timeline for when a secured account will become unsecured. Capital One
So avoid assuming:
“I’ve had my card for 12 months, so the issuer has to return my deposit now.”
Check the actual policy for your card.
If the card doesn’t offer the path you expected, you can then examine your alternatives rather than waiting indefinitely based on an assumption.
What If You Want the Deposit Back Before Graduation?
This is where the decision becomes more complicated.
You may have money tied up in the security deposit but an account that hasn’t graduated.
Closing the account might provide a route to recovering the deposit once the issuer’s requirements are satisfied. But closing a credit card is a separate decision and shouldn’t be made solely because you’re frustrated that the account hasn’t graduated yet.
Before closing it, determine:
- Whether the card has a graduation process.
- Whether your account is periodically reviewed.
- Whether the card charges an annual fee.
- What other credit accounts you currently have.
- What the issuer says will happen to the deposit after closure.
- Whether you actually need another card.
Then you can evaluate the trade-off.
Deposit Returned: What Changed on Your Terrain?
This is where CreditTerrain looks at the situation a little differently.
A returned security deposit is not merely a refund.
It can represent a change in how the account is structured.
Before graduation:
Your money → security deposit → secured account
After graduation:
Deposit returned → unsecured account continues → reassess the account
That doesn’t automatically mean you’ve reached “good credit.”
It doesn’t guarantee approval for another card.
And it doesn’t mean you should immediately close the account or apply for something new.
It means you’ve reached another credit checkpoint.
Now you can ask a better question:
Does the card that helped me get here still fit where I’m going next?
The Bottom Line
If your secured credit card graduates to unsecured status, you will generally get the security deposit back, but the refund method and timing depend on the issuer.
The money might arrive as a statement credit rather than a deposit into your bank account. Graduation also doesn’t automatically mean your credit limit, APR, rewards or other card terms will change.
So when that graduation notice arrives, check three things first:
How is my deposit being returned?
What changed about my account?
What, if anything, should I do next?
Recovering your deposit is worth noticing.
But the bigger opportunity is understanding what the transition means for the road ahead.
Continue Your CreditTerrain Path
If you’re approaching this transition, read What Happens When a Secured Credit Card Graduates to Unsecured? for the broader account changes to examine.
You can also continue through the Secured → Unsecured Credit Journey, use the Secured vs. Unsecured Credit Cards tool to understand the structural differences, or use Find My Card when you have a reason to examine other card options.
Sources
Consumer Financial Protection Bureau — research describing secured-card graduation practices, deposit returns and differences among issuer programs. Consumer Financial Protection Bureau
Capital One secured-card guidance — current information about secured-card deposits, upgrades and refund procedures. Capital One
Capital One secured-card deposit guidance — current explanation of security deposits and ways deposits may be returned. Capital One
Reviewed: October 2026
By: Michael Curtis