What Happens When a Secured Credit Card Graduates to Unsecured?
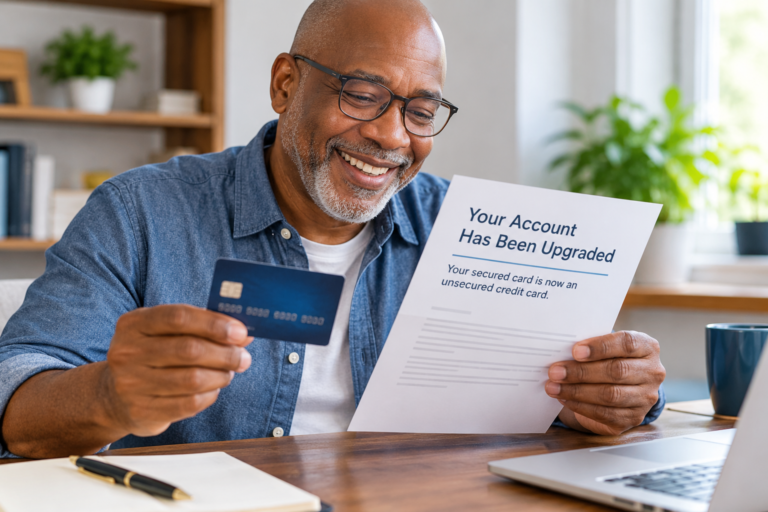
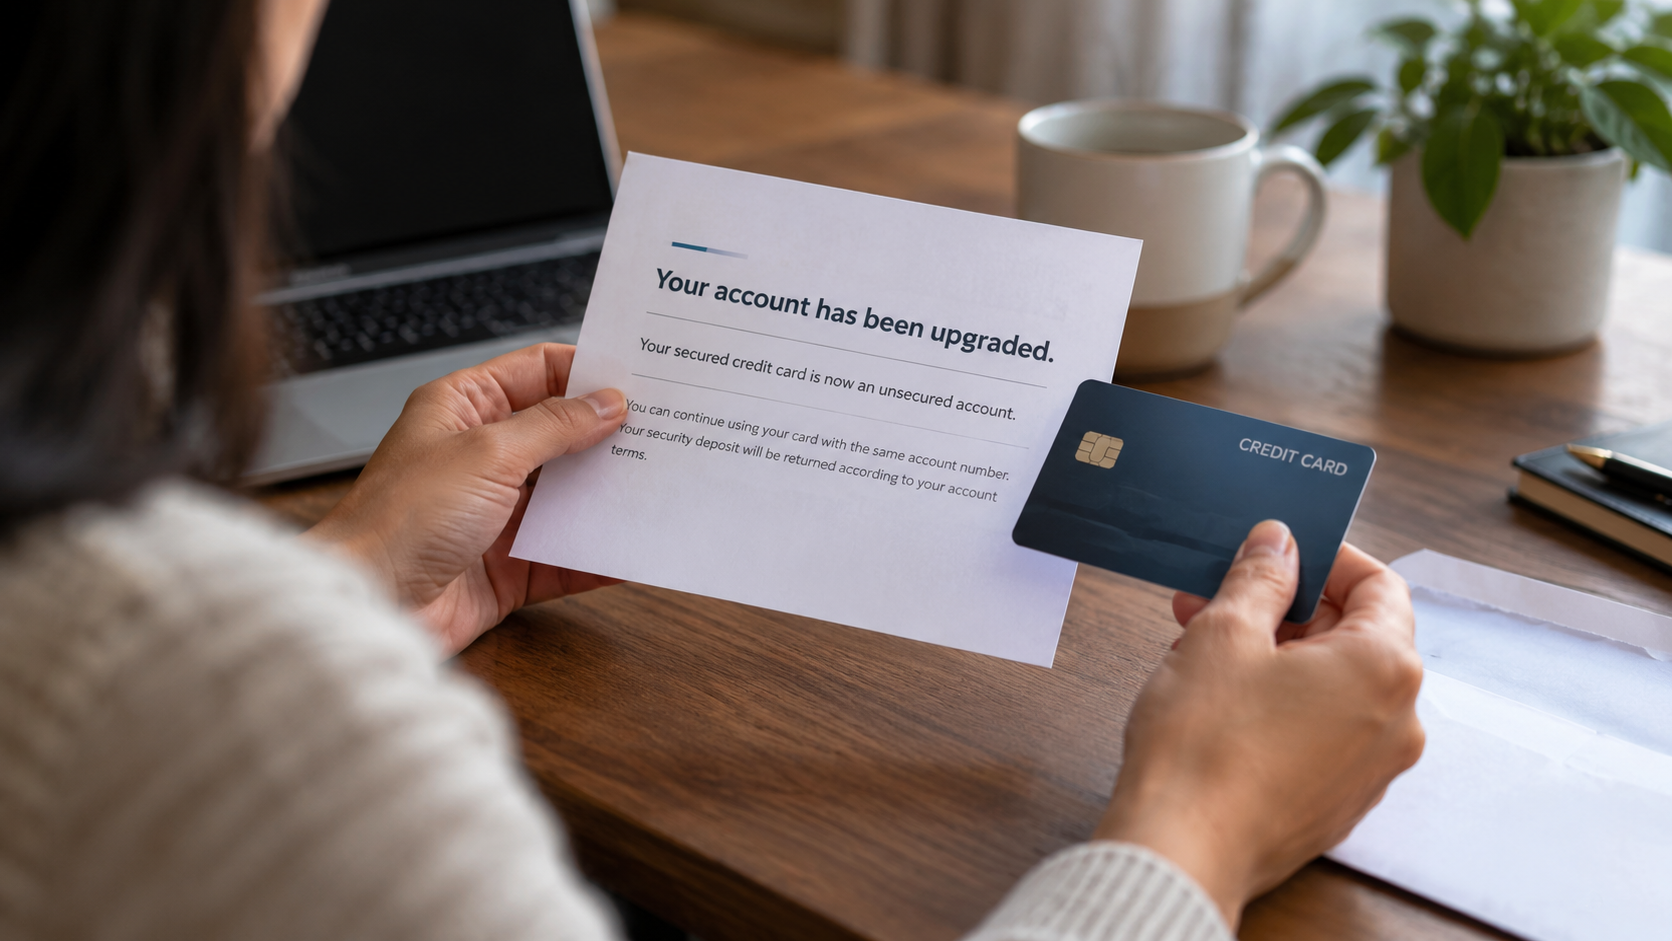
Getting a notice that your secured credit card is graduating to an unsecured card can feel like an important milestone. You may get your security deposit back, continue using the account without collateral, and have an opportunity to reconsider what you need from a credit card going forward.
But graduation does not necessarily mean everything about the account changes. Your credit limit, interest rate, rewards, fees, card number, or other terms may remain the same—or the issuer may handle some of them differently.
The important question is not simply, “Did my card graduate?”
It is:
What changed, what stayed the same, and what should I look at next?
That is where the secured-to-unsecured transition becomes more useful than the word graduation itself.
What Does It Mean When a Secured Credit Card Graduates?
A secured credit card generally requires a refundable security deposit. That deposit helps secure the account for the card issuer.
When the account graduates—or is converted—to unsecured status, the issuer no longer requires that security deposit for the account.
The Consumer Financial Protection Bureau notes that many secured cards include a graduation feature that can allow a cardholder to move to a traditional credit card after establishing a pattern of consistent payments. Consumer Financial Protection Bureau
Individual issuers establish their own graduation policies. Some periodically review secured accounts automatically. Others may have different requirements or may not offer a direct graduation path at all.
That distinction matters.
Using a secured card responsibly does not guarantee that a particular issuer will graduate your account by a certain date.
The First Big Change: Your Security Deposit May Come Back
For many cardholders, this is the most noticeable part of graduation.
If you originally put down $200, $500 or another amount to secure the card, graduation may allow that money to be returned because the issuer no longer needs it as collateral.
How the money comes back depends on the issuer.
For example, Capital One currently says that when an eligible secured account is upgraded to a traditional card, the security deposit is returned as a statement credit. Its policies also make clear that upgrade requirements vary by card. Capital One
Other issuers can use different procedures.
So don’t assume the deposit will immediately appear in your checking account.
Check:
- How your issuer returns the deposit
- When the refund should occur
- Whether it comes as a statement credit, check, bank transfer or another method
- Whether an outstanding balance affects the refund
This is one of those moments when the issuer’s current terms matter more than a general rule.
Does Your Credit Card Account Stay Open?
A graduation is different from closing a secured card and applying for an entirely new unsecured card.
When an issuer converts the existing account, you may be able to continue with that account rather than closing it simply to move away from secured credit.
That can be useful because closing an account is a separate financial decision with its own consequences.
Before doing anything after graduation, determine exactly what your issuer changed.
Look at the notice you received and your online account. If something isn’t clear, contact the issuer directly.
Don’t close the old account simply because you think graduating means you’re supposed to replace it.
Does Your Credit Limit Increase When a Secured Card Graduates?
Not necessarily.
Graduation and a credit-limit increase are two different events.
An issuer could unsecure an account while leaving the credit limit unchanged. Another issuer might separately evaluate the account for a higher limit.
This distinction is important because a returned deposit doesn’t automatically mean your available credit will increase.
For example, Capital One currently states for some of its secured-card products that the security deposit can be returned and the account unsecured while other card terms and features remain the same. Capital One
If your limit does change, consider what the new limit means for your overall credit utilization rather than treating additional available credit as additional money to spend.
What Happens to Your Credit Utilization?
Graduation itself doesn’t erase balances or change how credit utilization works.
Your utilization is generally the amount of revolving credit you’re using relative to the credit available to you.
For example, if your card still has a $1,000 credit limit and you’re carrying a $300 reported balance, graduation alone doesn’t change the basic relationship between those numbers.
If the issuer also increases your credit limit, however, the same balance could represent a smaller percentage of the available credit.
That’s why it’s useful to separate the events:
Graduation: the account no longer requires collateral.
Credit-limit increase: the amount of available credit changes.
They can happen together, but don’t assume they will.
CreditTerrain next step: Use the Credit Utilization Calculator to see your overall utilization and individual-card utilization before and after a credit-limit change.
Will Your APR Change?
This is another area where you should check the actual terms instead of assuming graduation automatically gives you a better interest rate.
The APR may stay the same. Terms can also vary by issuer and product.
That’s particularly important if you’ve improved your overall credit position while using the secured card.
A graduated account may be worth keeping, but that doesn’t automatically make its APR competitive with every other card you might now be able to consider.
If you normally pay your statement balance in full, the purchase APR may play a different role in your decision than it does for someone who regularly carries a balance.
The question becomes:
Does this card still fit the way I use credit now?
That’s a much better question than assuming “unsecured” automatically means “better in every way.”
What About the Annual Fee?
Check it.
A security deposit and an annual fee are completely different costs.
Getting your deposit back doesn’t necessarily eliminate an annual fee.
If the card continues charging one, look at what you’re receiving in return. That may include rewards, benefits or other features—but those benefits only have value if you actually use them.
This is exactly the kind of transition where our Annual Fee Break-Even Calculator can help put the cost into context.
If the card has no annual fee, keeping an older account open may present a different decision than keeping a card that costs you money every year.
Will the Card Start Earning Better Rewards?
Not automatically.
Graduation primarily concerns the secured status of the account. It doesn’t necessarily transform a basic secured card into a premium rewards card.
You might graduate and still have:
- The same rewards program
- No rewards
- The same APR
- The same credit limit
- The same card benefits
That doesn’t mean graduation wasn’t valuable.
Getting your deposit returned while retaining an account can itself be meaningful.
But it does mean you should separate graduation from product upgrade.
They aren’t always the same thing.
Does Graduation Mean Your Credit Is Now “Good”?
No.
This is one of the most important distinctions to understand.
An issuer’s decision to graduate a secured account is a decision about that particular account under that issuer’s policies. It isn’t an official declaration that you’ve entered a universal credit-score category.
Credit decisions can consider multiple factors, and scoring models don’t necessarily use identical ranges or labels.
So CreditTerrain would not interpret a graduation notice as:
“Congratulations. You now have good credit.”
We would interpret it more carefully:
One part of your credit terrain may have changed. Now examine what that change makes possible.
That’s much more useful.
Your Secured → Unsecured Checkpoint
Once your card graduates, work through these questions before making another move.
| Check | What to Look For |
|---|---|
| Security deposit | Is it being returned, and how? |
| Account status | Is the existing account continuing as unsecured? |
| Credit limit | Did it stay the same or change? |
| APR | Is the purchase APR different? |
| Annual fee | Does the card still charge one? |
| Rewards | Did the rewards structure change? |
| Card benefits | Were any benefits added or removed? |
| Card number | Will you continue using the same card/account details? |
| Credit reporting | How will the account continue to be reported? |
| Next move | Does this card still fit your needs? |
You don’t need to make another credit-card move simply because your secured account graduated.
Sometimes the best next step is simply to continue managing the account well.
Should You Apply for Another Credit Card After Graduation?
Maybe—but graduation by itself isn’t a reason to submit another application.
First ask what you’re trying to accomplish.
Are you looking for:
A higher credit limit?
See whether your current issuer provides a path to one.
Cash back or other rewards?
Compare the value of another card with what you already have.
No annual fee?
Check whether your graduated card already provides that.
A lower APR?
Compare current terms, especially if you sometimes carry balances.
Another account to increase available credit?
Consider the entire credit picture rather than opening an account solely to chase a utilization percentage.
A new application can also involve a hard credit inquiry, depending on the issuer and process. Don’t turn a positive milestone into a reason to apply for several cards at once.
What If Your Secured Card Hasn’t Graduated?
Don’t assume something is wrong.
Issuer policies vary.
Some issuers periodically review accounts for graduation. Some cards may have different eligibility requirements, timelines or processes. Some secured products may not offer the graduation path you’re expecting.
Capital One, for example, says it periodically reviews eligible secured accounts and that its secured cards cannot simply be upgraded by request. Capital One
If you’ve had the card for a while, you can check the issuer’s current policy and ask:
- Does this card have a graduation path?
- Are accounts reviewed automatically?
- Can I request a review?
- What happens to my deposit?
- Would moving to another product require a new application?
- Would closing the account be required to receive my deposit?
Get the answers for your specific account before making a decision.
Should You Close the Secured Card Instead?
Not simply because you’ve become eligible for other credit cards.
Closing an account and graduating an existing account aren’t equivalent.
If your issuer can convert the existing card to unsecured status and return the deposit, that may give you another route besides closing it.
If the card cannot graduate, charges an annual fee you no longer consider worthwhile, or no longer fits your needs, then closing it may deserve consideration.
But evaluate the decision rather than treating closure as the automatic next step.
Our separate guide, Should I Close My Secured Credit Card After Getting an Unsecured Card?, will examine that decision in more detail.
The Bigger Change Isn’t the Label on the Card
Graduating from a secured card can be an encouraging milestone, especially if the account helped you establish or rebuild credit.
But the most useful part of the transition isn’t simply removing the word secured.
It’s the opportunity to reassess your position.
You may now have your deposit back. Your account may remain open. Your available options may be different. Your priorities may also have changed since you originally applied for the secured card.
That’s why CreditTerrain treats Secured → Unsecured as a transition rather than a finish line.
The road doesn’t end when the deposit comes back.
You reached a checkpoint. Now you can decide what—if anything—needs to change next.
Continue Your CreditTerrain Path
If your secured card has graduated—or you’re waiting for that transition—start with our Secured → Unsecured Credit Journey. It walks through the questions to examine before closing an account, applying for another card, or deciding that your current setup already works.
You can also use the Secured vs. Unsecured Credit Cards tool to examine how the two structures differ, or Find My Card when you’re ready to look at card options based on your current situation and priorities.
Sources
Consumer Financial Protection Bureau — guidance on secured cards and rebuilding credit. Consumer Financial Protection Bureau
Capital One — current guidance on secured-card deposits and upgrades. Capital One
Experian — guidance on secured-card upgrades and deposit refunds. Experian
Reviewed: October 2026
By: CreditTerrain Editorial Team